
Stamp Duty Savings, Rising Interest Rates and the 5% Deposit Scheme Explained
October 2026 | Tomoro Real Estate
Buying your first home in Toowoomba is an exciting milestone, but understanding the financial side of purchasing property has become increasingly important. Between Queensland's first-home buyer stamp duty concessions, changing interest rates and the Australian Government's 5% Deposit Scheme, there are several important thresholds that could influence how much you need to save, borrow and repay.
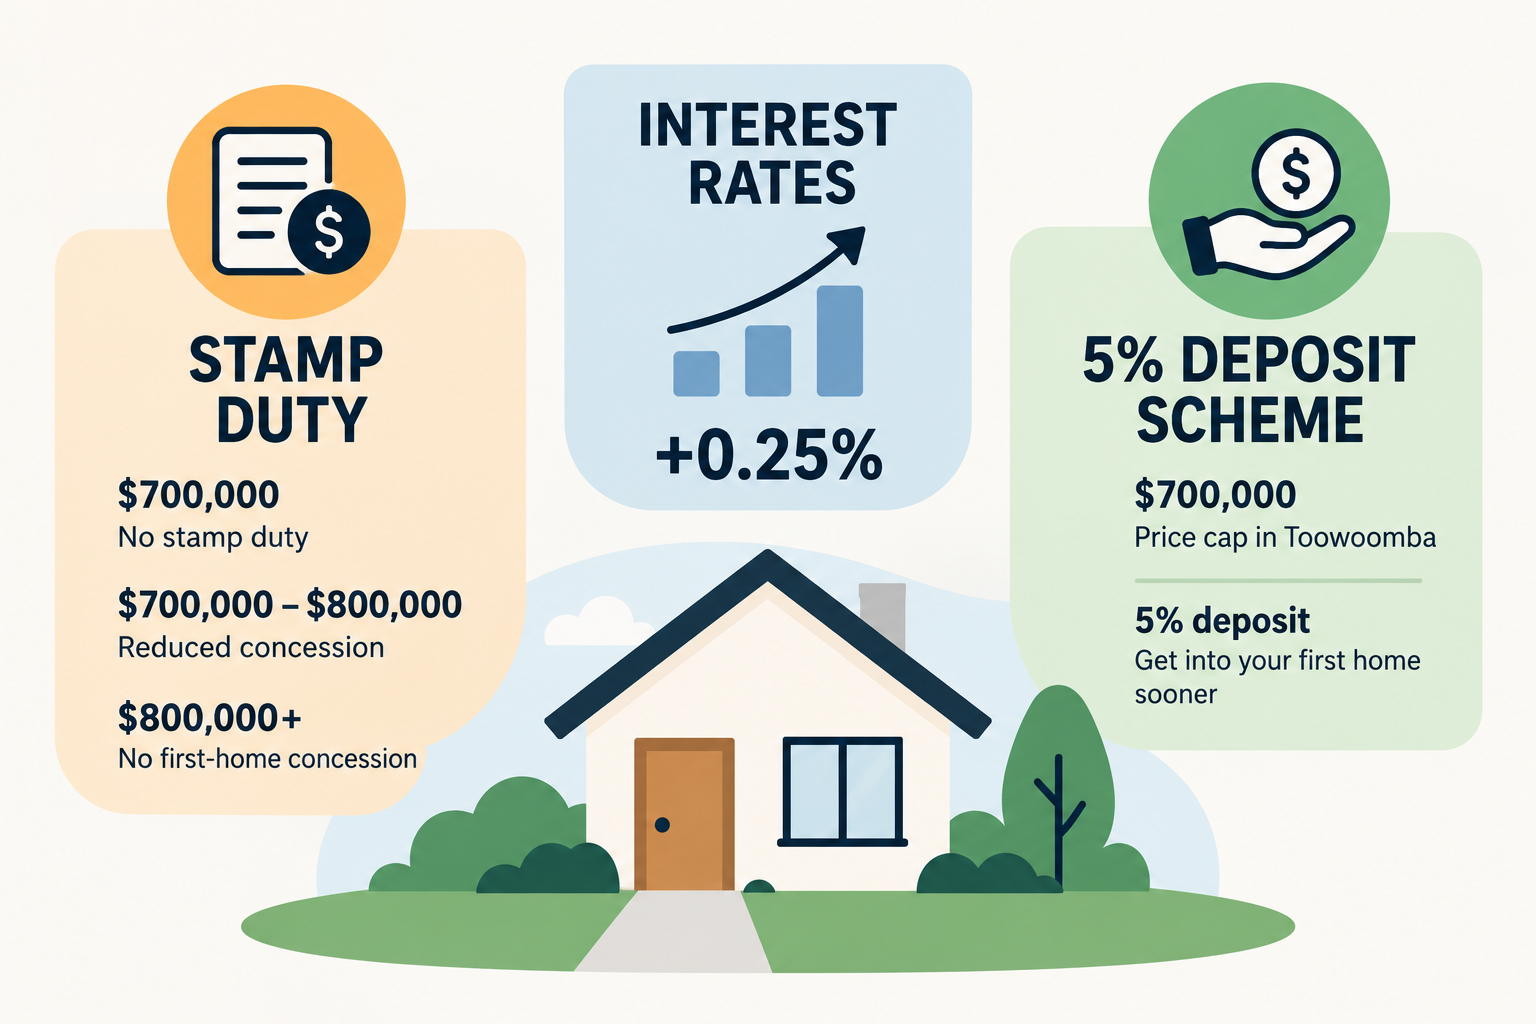
For first-home buyers, three figures deserve particular attention: $700,000, $800,000 and 0.25%.
The first two relate to government assistance and property price limits, while the third represents the size of a recent Reserve Bank interest rate increase.
Understanding how these figures work together could make a significant difference to your purchasing decisions.
1. Queensland's $800,000 Stamp Duty Threshold: What First-Home Buyers Need to Know
Stamp duty, officially known as transfer duty in Queensland, is one of the largest upfront expenses associated with purchasing property.
Fortunately, Queensland offers substantial concessions to eligible first-home buyers purchasing established residential properties.
Under the current arrangements:
-
Properties valued at $700,000 or less: Eligible first-home buyers pay no transfer duty.
-
Properties valued between $700,000 and $800,000: A reduced concession applies, gradually decreasing as the property value increases.
-
Properties valued at $800,000 or more: The specific first-home concession no longer applies, although buyers may still qualify for the general home concession.
These concessions can save eligible first-home buyers up to $24,525 in transfer duty.
Why the $800,000 threshold matters
Consider a first-home buyer searching for property in suburbs such as Glenvale, Harristown, Kearneys Spring or Highfields.
A property priced at $695,000 could qualify for a full first-home transfer duty concession, while an established property priced at $750,000 would attract some transfer duty.
At $800,000, the specific first-home concession is no longer available.
This means buyers should look beyond the advertised purchase price and calculate their total acquisition costs before making an offer.
What about newly built homes?
Queensland provides additional assistance for eligible first-home buyers purchasing newly constructed homes.
For contracts signed from 1 May 2025, qualifying first-home buyers can receive a full transfer duty concession on a new home, regardless of the property's value.
A similar concession is available for eligible purchases of vacant land to build a first home.
This creates an important distinction between established properties and newly constructed homes.
For buyers considering a brand-new home in developing Toowoomba estates, these concessions could substantially reduce upfront purchasing costs.
However, eligibility conditions apply, including residency and occupancy requirements. From 1 August 2026, Queensland also introduced citizenship and residency eligibility changes for home concessions.
2. Rising Interest Rates: What an Extra 0.25% Means for a $600,000 Mortgage
Interest rates remain one of the biggest factors influencing housing affordability.
On 29 September 2026, the Reserve Bank of Australia increased the official cash rate by 0.25 percentage points to 4.60%, continuing its efforts to contain inflation.
Although a quarter-percentage-point increase may appear relatively small, its impact accumulates over the life of a mortgage.
How much does a 0.25% increase cost?
Consider a buyer with a $600,000 home loan over 30 years, making principal-and-interest repayments.
If their mortgage interest rate increases from 6.00% to 6.25%, the approximate impact is:
| Repayment comparison | Before increase | After increase |
|---|---|---|
| Loan amount | $600,000 | $600,000 |
| Interest rate | 6.00% | 6.25% |
| Monthly repayment | $3,597 | $3,694 |
| Annual repayments | $43,168 | $44,332 |
Additional mortgage cost
+$97 per month
Approximately $1,164 more per year.
Illustrative calculations assume a 30-year principal-and-interest loan, unchanged remaining term and full pass-through of the rate increase. Actual lender rates and repayments vary.
While an additional $97 per month may be manageable for some households, it represents another ongoing expense at a time when buyers are also navigating rising living costs, insurance premiums and household expenses.
Interest rates also influence borrowing capacity
Higher interest rates don't just affect existing homeowners. They can also influence how much prospective buyers can borrow.
Australian lenders assess borrowers' ability to service a mortgage using interest rates above the actual loan rate, together with household income, living expenses and existing debts.
When mortgage rates increase, borrowing capacity can decline, potentially reducing the maximum purchase price a buyer can afford.
For Toowoomba first-home buyers, this highlights the importance of obtaining finance pre-approval and reviewing borrowing capacity before making an offer.
Rather than focusing exclusively on the maximum amount a bank will lend, buyers should consider repayments that remain comfortable if interest rates increase further.
3. The Australian Government's 5% Deposit Scheme: Understanding Toowoomba's $700,000 Price Cap
Saving a deposit remains one of the largest obstacles facing first-home buyers.
Traditionally, buyers seeking to avoid lenders mortgage insurance (LMI) have generally needed a deposit of approximately 20% of the purchase price.
The Australian Government's 5% Deposit Scheme offers an alternative for eligible buyers.
Under the scheme, eligible first-home buyers can purchase a property with a deposit as low as 5%, supported by a government guarantee that enables participating lenders to offer eligible loans without LMI.
However, the scheme has property price caps that vary by location.
What is the price cap for Toowoomba?
Toowoomba — 5% Deposit Scheme
$700,000
Maximum eligible property price under the current regional Queensland cap.
Minimum 5% deposit
$35,000
95% loan
$665,000
Toowoomba falls within the scheme's regional Queensland category, where the property price cap is $700,000. This differs from Brisbane, the Gold Coast and the Sunshine Coast, which have a $1 million cap.
For a $700,000 property, an eligible buyer could potentially purchase with a $35,000 deposit rather than the $140,000 deposit ordinarily associated with a 20% contribution.
That represents a difference of $105,000 in the deposit required.
Importantly, the government does not provide the deposit or repay part of the mortgage. Buyers still need to meet lender serviceability requirements and cover applicable purchasing costs.
The challenge for Toowoomba buyers
The $700,000 price cap creates an important consideration for buyers searching in Toowoomba.
A property priced at $695,000 may qualify under the scheme, subject to eligibility and lender approval.
However, a property priced at $720,000 would exceed the current cap, even if the buyer had sufficient income to service the loan.
This could influence property searches, particularly for buyers considering larger family homes, newer properties or premium locations.
Buyers should also be aware that the scheme's $700,000 property price limit is separate from Queensland's $800,000 first-home transfer duty concession threshold.
4. How the Three Measures Work Together
Understanding each policy individually is useful, but their combined impact is even more important.
Consider three hypothetical first-home buyers purchasing established properties in Toowoomba.
| Purchase price | Stamp duty position | 5% Deposit Scheme |
|---|---|---|
| $650,000 | Full first-home concession potentially available | Potentially eligible |
| $750,000 | Partial first-home concession potentially available | Above price cap |
| $825,000 | No specific first-home concession; general home concession may apply | Above price cap |
Assumes qualifying first-home buyers purchasing established homes. Other eligibility requirements apply.
For eligible buyers purchasing established properties at or below $700,000, there is an opportunity to benefit from both the Queensland transfer duty concession and the Australian Government's 5% Deposit Scheme.
However, these incentives should not automatically determine how much someone spends on a home.
A lower deposit means borrowing a larger proportion of the purchase price, which can result in higher repayments and more interest over time.
For example, purchasing a $700,000 property with a 5% deposit leaves a $665,000 mortgage. That is a significantly larger loan than purchasing the same property with a 20% deposit.
The savings in upfront costs should therefore be considered alongside the longer-term financial commitment.
5. Should First-Home Buyers Purchase Now or Wait?
There is no universal answer to whether now is the right time to purchase a first home.
For some buyers, the combination of stamp duty concessions and low-deposit financing may provide an opportunity to enter the market sooner.
For others, taking additional time to build savings, reduce existing debts or improve borrowing capacity may be the more appropriate decision.
Before purchasing, first-home buyers should consider several factors.
Your deposit and cash reserves: A deposit is only part of the upfront financial commitment. Buyers should also budget for conveyancing, building and pest inspections, moving expenses and an emergency fund.
Your mortgage repayments: Assess affordability based on realistic household expenses and allow room for unexpected costs or further interest rate changes.
Your preferred location: Property prices and housing options vary considerably across Toowoomba. Buyers may need to balance location, property size, age and future maintenance requirements.
Your long-term plans: Purchasing a property should ideally align with your employment, family circumstances and expected housing needs.
Your eligibility for assistance: Confirm which government schemes and concessions apply to your circumstances before signing a contract.
6. What Does This Mean for the Toowoomba Property Market?
Government assistance schemes and interest rate movements can influence buyer behaviour across the local property market.
The $700,000 threshold may encourage eligible buyers to focus on properties within that price range, particularly where both the deposit scheme and stamp duty concessions are available.
This could support demand for more affordable established homes, units and townhouses, although actual market outcomes will also depend on available listings, borrowing capacity and broader economic conditions.
Meanwhile, Queensland's transfer duty concessions for newly built homes may make new construction more appealing to qualifying buyers.
Higher interest rates work in the opposite direction by increasing borrowing costs and potentially limiting purchasing power.
For sellers, understanding these competing influences is important when establishing an asking price and developing a marketing strategy.
For buyers, the key is to understand what assistance is available without allowing a government incentive to outweigh the fundamentals of purchasing a suitable, affordable property.
Final Thoughts: Understand the Numbers Before Buying
Purchasing your first home in Toowoomba involves more than saving a deposit and finding a property you love.
Queensland's transfer duty concessions, the Australian Government's 5% Deposit Scheme and changing interest rates can all influence the true cost of buying a home.
The most important figures to remember are:
-
$700,000: The full first-home transfer duty concession threshold for eligible established homes and the current 5% Deposit Scheme property price cap in Toowoomba.
-
$800,000: The upper threshold for Queensland's first-home transfer duty concession on established homes.
-
0.25%: The size of the September 2026 RBA rate increase, demonstrating how relatively small changes can affect mortgage repayments.
Taking the time to understand these thresholds, speak with a qualified mortgage broker and obtain independent legal advice can help buyers make informed decisions.
At Tomoro Real Estate, we work with buyers across Toowoomba, Highfields and surrounding communities, helping them understand local property options and navigate the purchasing process.
Whether you're searching for your first home, considering a newly built property or exploring opportunities within the $700,000 price cap, understanding the local market is an important first step.
Thinking about buying your first home in Toowoomba? Contact the team at Tomoro Real Estate to discuss available properties and opportunities across the region.
You might also be interested in
Sep 14, 2026
Your Guide to the Garden City in Bloom Spring in Toowoomba means one thing: the Garden City is about to burst into colour. The Toowoomba Carnival of Flowers 2026 runs from Friday 18 September to Monda
Jul 29, 2026
What Could It Mean for Interest Rates and Toowoomba Property? Australia’s latest inflation figures have delivered some encouraging news for households, borrowers and the property market, with annual i